Wondering how much professional liability insurance will cost your business in 2026? Many small businesses in the United States pay around $88 per month, according to Insureon data. However, the professional liability cost depends on your profession, business income, and coverage needs.
A freelancer may pay less than a firm handling large client projects. Knowing what affects the average cost for liability insurance helps you compare quotes.
What Is the Average Cost of Professional Liability Insurance?
Planning your business expenses? The average cost of professional liability insurance is around $88 per month for small businesses, based on Insureon’s reported median premium.
Here is a quick breakdown:
| Payment period | Estimated cost |
| Monthly | $88 |
| Quarterly | $264 |
| Annually | $1,051 |
These figures are estimates, not guaranteed quotes. Your actual professional liability cost will depend on your business and insurer.
How Much Does Insurance Cost for Different Businesses?
Not every profession pays the same rate. An IT consultant may face claims involving software errors, while an accountant may need protection against financial mistakes.
| Business type | Example annual cost |
| IT consultant | $515 |
| Business consultant | $1,025 |
| Real estate agent | $816 |
| IT or software developer | $1,320 |
Examples from published Hiscox and Insureon pricing data. Actual premiums vary by business profile and policy.
Before choosing a policy, compare coverage limits, deductibles, and exclusions. A cheaper plan may not offer the protection your business needs.
What Affects Professional Liability Insurance Rates?
Why might one business pay more than another? Insurers usually consider these factors:
- Your profession: Work that could cause clients significant financial losses may carry higher premiums.
- Business income: Revenue, client numbers, and project sizes can affect your quote.
- Coverage limits: Higher limits generally cost more, so choose protection that suits your contracts and risks.
- Claims history: Previous claims may affect the price an insurer offers.
Understanding these factors can help you make a more informed decision about your professional liability cost.
What Does Professional Liability Insurance Cover?
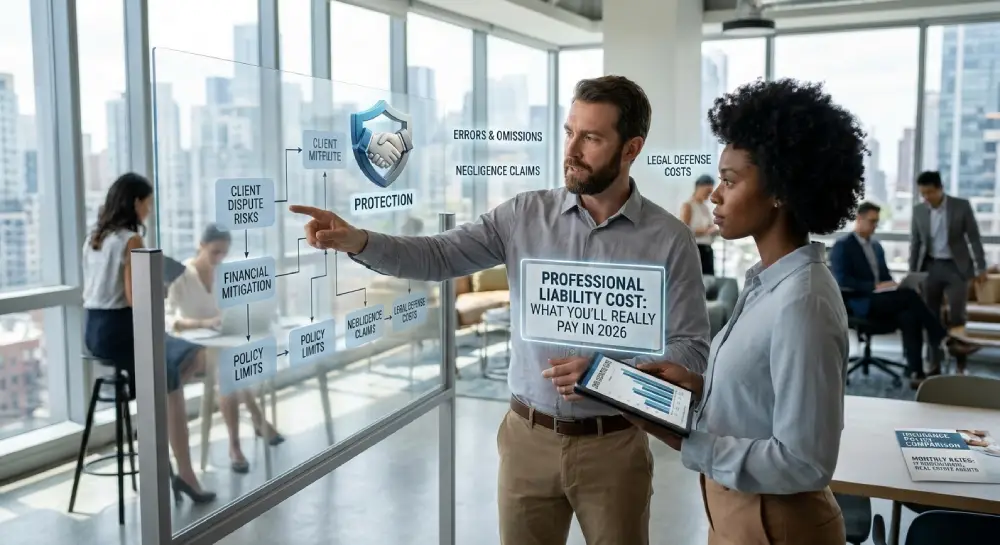
What happens if a client claims your work caused a financial loss? Depending on your policy, professional liability insurance may help cover:
- Professional errors: Mistakes made while providing services.
- Negligence claims: Allegations that your work failed to meet professional standards.
- Omissions: Certain claims involving overlooked responsibilities.
- Legal defense costs: Eligible legal expenses for covered claims.
Remember, exclusions and coverage limits apply. Always read the policy before purchasing it.
How Can You Lower Your Insurance Costs?
You do not have to accept the first quote you receive. Try these simple steps to manage your professional liability cost:
- Compare quotes: Check prices from several insurers with similar coverage.
- Choose suitable limits: Get enough protection without paying for unnecessary coverage.
- Ask about discounts: Some insurers offer discounts on eligible bundled policies.
- Keep clear records: Written agreements and client approvals can help prevent disputes.
- Review your policy yearly: Update coverage when your business grows or services change.
Is Professional Liability Insurance Worth It?
If you provide consulting, technical services, or professional advice, a single claim could lead to expensive legal bills. The professional liability cost may be a worthwhile business expense if it protects you against covered claims that you could struggle to pay yourself.
Review policy options and exclusions, deductibles, and legal defense coverage before selecting a policy. Right coverage should match your business and risk coverage.
Frequently Asked Questions
How much does professional liability insurance cost monthly?
Insureon data indicates that many small businesses pay more or less than $88 per month. Coverage limits, claims history, location, profession and revenue are just a few of the factors that can influence your premium.
Why do insurance rates differ by profession?
Some professions face greater risks of expensive claims. For example, financial mistakes or software errors can cause significant client losses, which may lead to higher premiums.
Is professional liability insurance required?
Requirements vary with your career, geographic area and client contracts. Some insurance may be required although not necessarily by law, and some clients may ask for proof of insurance before beginning a project.
What is the difference between professional and general liability insurance?
Professional liability typically includes qualified claims for professional errors or negligence. Typically, general liability includes coverage of some bodily injury, property damage, and personal or advertising injury claims.
Can freelancers buy professional liability insurance?
Yes. A large number of insurance providers have insurance policies tailored to the needs of independent workers and freelancers. The cost will be based on your services, income, claims record, and coverage options.
Does professional liability insurance cover legal fees?
Many policies cover eligible legal defense costs for covered claims. But these costs can cut into your coverage amount, based on policy terms.
Can premiums increase at renewal?
Yes. Premiums can go up when there are claims, business expansion, coverage changes, or adjustments by the insurer. One way to find competitive coverage is to compare quotes for renewal.
Is professional indemnity insurance the same as professional liability insurance?
The terms often describe similar protection, but usage varies by country and insurer. Review policy terms and conditions to see what is covered and what is not.
How much coverage does a small business need?
This is based on your job, contracts and estimated costs of any claims. Some companies opt for $1 million coverage, and others may require other limits for their needs.
How can you get an accurate insurance quote?
Gather information about your services, income, staffing, address and claims. Shop around and review the policy coverage limits, deductibles and exclusions before selecting a policy.